Making Tax Digital for sole-trader builders: prepare your first autumn update
Already using Making Tax Digital for Income Tax? Get your building business records organised, check your next deadline and resolve receipt and payment queries before submitting.
HappyNoodle30 September 2026 4 min read
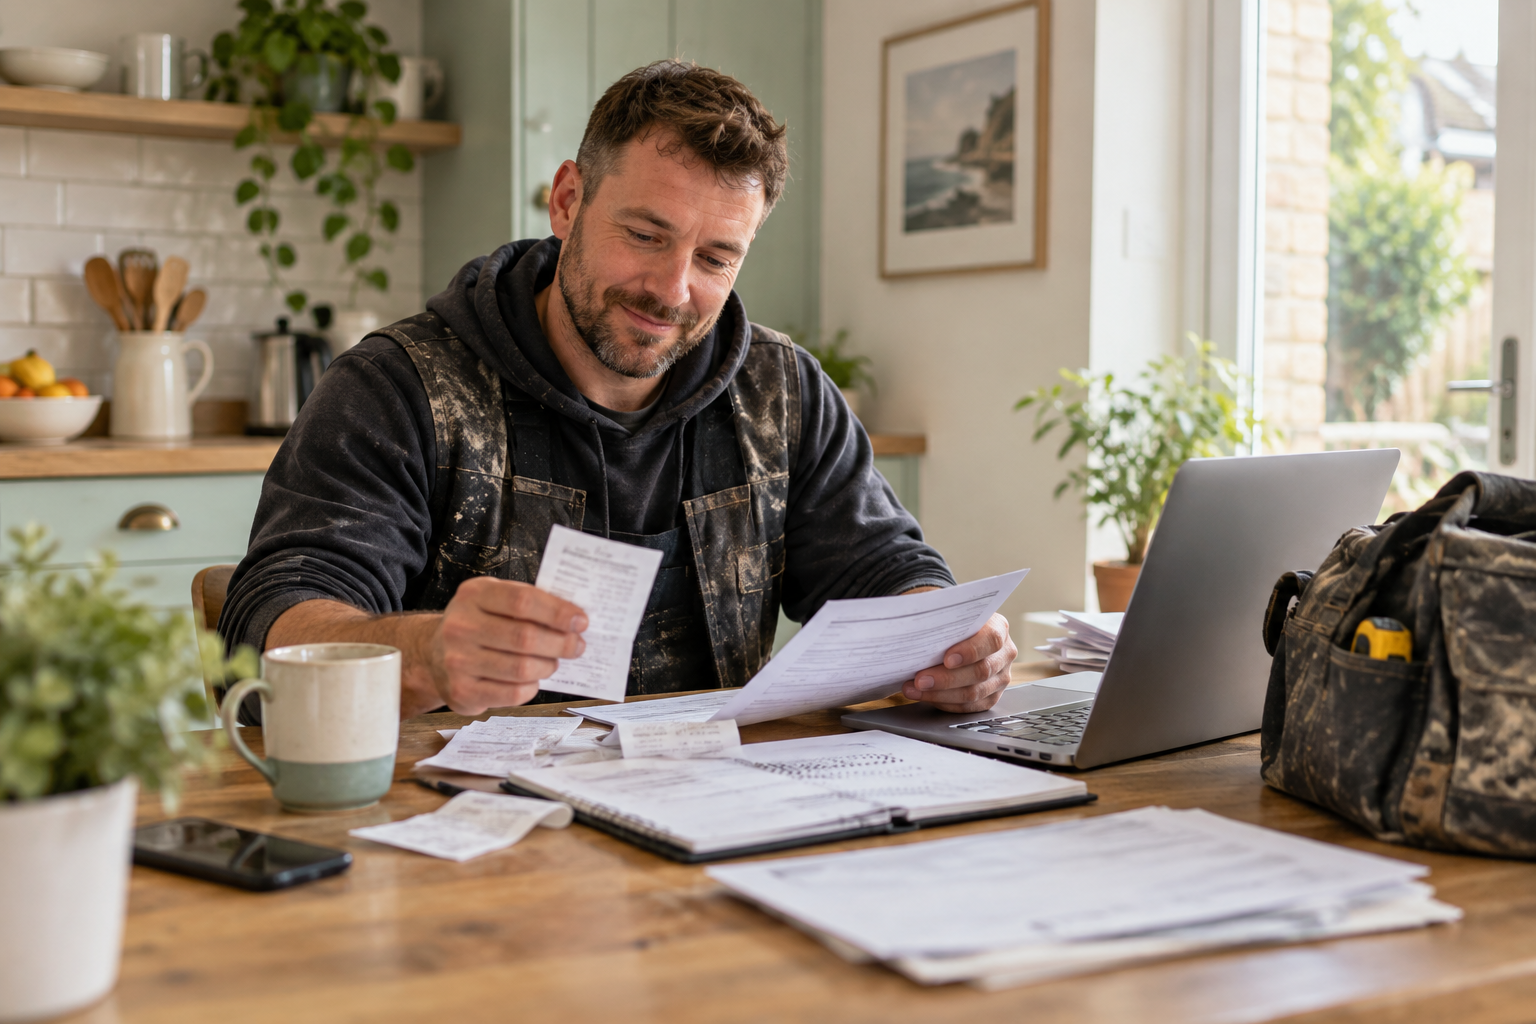
When you are juggling deliveries, subcontractors and customer changes, bookkeeping can slip behind the building work. Preparing your next autumn update is a useful reason to bring those records together before a missing merchant receipt becomes a lengthy search. This guide to Making Tax Digital for builders focuses on sole traders already using Making Tax Digital for Income Tax, rather than limited-company businesses. The practical task is to make your records clear enough to review: what customers paid, what you bought, which entries need checking and who will submit the update. Start by confirming your reporting period and deadline with HMRC, then work through your software with your bookkeeper or accountant where needed. Below is a site-friendly preparation checklist, with particular attention to materials, customer payments and Construction Industry Scheme (CIS) paperwork. This is general information, not legal, tax or financial advice.
Key takeaways
- Check qualifying income, not profit. HMRC describes qualifying income as total self-employment and property income before expenses. Check the applicable starting threshold, reference tax year and exemptions on GOV.UK.
- Confirm the reporting period before reviewing transactions. Ask HMRC or your adviser to confirm the period and submission deadline that apply to you, rather than assuming your usual bookkeeping dates match.
- Choose software around the way you work. Check Income Tax compatibility and test practical tasks such as recording a merchant receipt, matching a payment and sharing records with your adviser.
- Keep CIS paperwork alongside the related invoices. Gather payment and deduction statements so your adviser can check the treatment of gross amounts, deductions and money received.
- Resolve gaps before submitting. Review missing receipts, possible duplicates and unexplained payments, then confirm who will submit and check the submission outcome.
Check whether you fall within the April 2026 starting group
HMRC’s guidance says that some sole traders and landlords must use Making Tax Digital for Income Tax from 6 April 2026, based on their total annual self-employment and property income. If you are already using it, keep your enrolment details and any HMRC correspondence with your tax records.
The important distinction is income before expenses, not the profit left after paying for materials, labour and other costs. HMRC calls this qualifying income and says it can include more than one source of self-employment or property income. Looking only at the profit from your building work is therefore not the right eligibility check.
Confirm the starting threshold, the tax year HMRC uses to assess you and any applicable exemptions against current GOV.UK guidance or with your accountant. Do not rely on a social-media summary or assume that joining voluntarily and being required to join are the same thing.
Confirm your quarterly periods and submission deadlines with HMRC
Before sorting transactions, confirm the reporting period and submission deadline that apply to your next update. Check current HMRC guidance and the setup in your software; if the dates appear inconsistent, ask your adviser to resolve that before you submit.
Agree who is responsible for preparing, reviewing and submitting the update. A bookkeeper organising your records does not, by itself, tell you who has agreed to handle submission. Put an internal review date in your diary with enough room to chase missing paperwork.
HMRC’s quarterly update direction says the information required depends on the relevant business activity or activities. If you have property income or another business alongside building work, ask your adviser how each should be handled rather than combining everything without checking.
- Confirm the reporting period covered by the next update.
- Check the submission deadline against current HMRC information.
- Name the person preparing, reviewing and submitting it.
- Agree how you will check and retain the submission confirmation.
Choose compatible software that fits site-based work
If your current setup is working, focus on checking it rather than replacing it just before an update. If you are choosing or changing software, confirm its suitability for Making Tax Digital for Income Tax through current GOV.UK guidance and the provider. Ask specifically about your business and any adviser access you need.
Test the everyday jobs that matter on site: capturing a readable merchant receipt, adding a note about the job, finding an invoice and reviewing a customer payment. Ask what happens when your phone has no signal and whether anything needs checking after records synchronise.
Treat automation as a draft to review, not proof that the entry is right. Check suggested categories and possible matches against the original paperwork. If a tool uses AI to read receipts, review the supplier, date and amount before accepting the result.
Organise materials, customer payments and CIS deductions
Bring together merchant invoices, receipts, credit notes and customer payment records. Add a job reference where it helps you identify the transaction later. For returned materials, keep the credit note with the purchase paperwork so the adjustment is visible during review.
Match customer payments to the relevant invoice or job record. Flag deposits, stage payments and amounts covering several invoices for review where the treatment is unclear. Ask your bookkeeper how to record them under your accounting setup rather than choosing a category simply to clear the transaction list.
Where CIS deductions are involved, gather the contractor’s payment and deduction statement alongside your invoice and bank receipt. Ask your accountant to check how the gross payment and deduction should be recorded; do not assume the net amount arriving in the bank tells the whole story.
- Materials: collect invoices, receipts and related credit notes.
- Customer money: identify the payer and the invoice or job it relates to.
- CIS: gather payment and deduction statements and flag missing documents.
- Unclear entries: keep a short query list for your bookkeeper rather than guessing.
Fix missing receipts and duplicate transactions before updating
Review your records against the supporting paperwork and bank activity. Look for unexplained amounts, purchases without evidence and entries that appear more than once. Check possible duplicates carefully: similar purchases from the same merchant may both be genuine.
For a missing receipt, try the supplier’s account portal or request a copy. Add a note describing the purchase and the job while you can still remember it. If evidence remains unavailable, ask your adviser how to handle the entry rather than assuming a bank transaction settles its tax treatment.
When an imported bank item and an existing invoice appear to describe the same transaction, check your software’s matching process before deleting anything. The aim is a clear record that you and your adviser can follow, not merely an empty list of notifications.
- 1Collect outstanding supplier paperwork and CIS statements.
- 2Match customer receipts and supplier payments to their supporting records.
- 3Investigate apparent duplicates, refunds and unexplained transactions.
- 4Send unresolved questions to your adviser with the relevant documents.
- 5Review the proposed update and confirm who will submit it.
Understand what quarterly updates do and do not replace
Treat preparation of the quarterly update as a defined reporting task, not a complete review of every tax obligation. HMRC publishes a specific direction for quarterly update information; check current GOV.UK guidance or ask your accountant what your update must contain.
Do not assume that sending an update means all year-end work is finished or that a tax payment has been made. Confirm separately what final reporting, adjustments and payment obligations remain for your circumstances, including how any other business tax responsibilities fit alongside Income Tax reporting.
After submission, check the outcome in the software and keep the confirmation with your working records. Note any follow-up questions and agree how corrections should be handled. That gives you a clearer starting point for the next review instead of leaving uncertainties buried in messages.
Put this into practice
How Invoices and payments helps
Create invoices from the work, make payment simple and keep polite reminders connected to the right client.
Explore Invoices and paymentsCommon questions
Is qualifying income my turnover or my profit?
HMRC describes qualifying income as total self-employment and property income before expenses, also known as turnover. It is not the profit left after your business costs. Check current GOV.UK guidance for the applicable threshold, reference tax year and exemptions.
Does rental income count alongside my building income?
HMRC says qualifying income includes self-employment and property income and may come from more than one source. If you have both, ask your adviser to check your overall position and how the activities should be reported.
What is the deadline for my next autumn update?
Confirm your reporting period and submission deadline using current HMRC guidance, your software and your adviser. Do not assume that a date used for another tax obligation is also your Income Tax update deadline.
How should I deal with customer payments subject to CIS deductions?
Keep the invoice, contractor’s payment and deduction statement, and bank receipt together. Ask your accountant to confirm the correct recording of the gross payment and deduction rather than relying only on the net bank receipt.
What should I do if a merchant receipt is missing?
Check the merchant’s portal or request a copy, and record what the purchase related to. If you cannot obtain supporting paperwork, ask your adviser how to handle the transaction before finalising your records.
Does submitting an update mean my tax work is finished?
Do not treat the submission as confirmation that every tax obligation is complete. Check with GOV.UK or your accountant what year-end reporting, adjustments and payments remain, and retain the update’s submission confirmation.
Sources
- Benefits of Making Tax Digital - GOV.UK
- Work out your qualifying income for Making Tax Digital for Income Tax
- Making Tax Digital for Income Tax: quarterly update direction - GOV.UK
- Making Tax Digital Explained: HMRC Rules for UK Businesses - RSBC
General information only, not legal, tax or financial advice. Check GOV.UK or a qualified adviser for your situation.
Make your next update a planned job
Set aside a bookkeeping session, gather your merchant and CIS paperwork, and send your adviser a focused query list. Confirm the reporting period, deadline and submission responsibility before returning to site.
Explore Invoices and payments